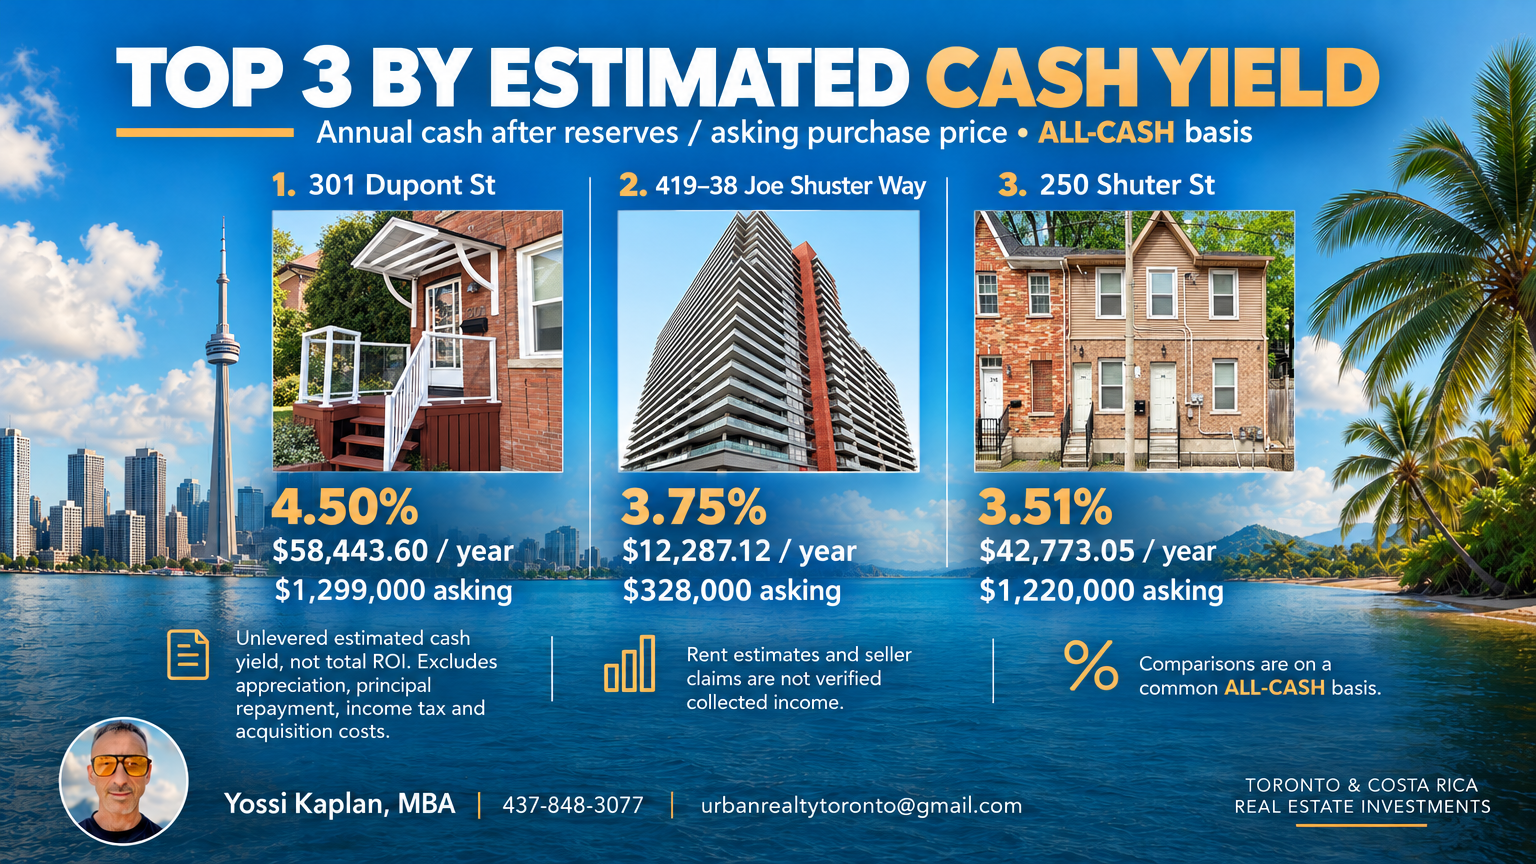
Common all-cash basis; not total ROI or a guarantee. AI-generated graphic using actual listing photographs.
Ranking methodology: “ROI” here means unlevered estimated cash yield: annual estimated cash after taxes, fees, owner-bill allowances, insurance, vacancy, repairs/capital replacement and management reserves, divided by asking purchase price. Every property uses 100% cash / 0% mortgage—not a financed cash-on-cash return. Excludes appreciation, principal repayment, income tax, acquisition costs and initial capital work. Unrounded original inputs give 301 Dupont $58,443.60/year (4.50%), 419–38 Joe Shuster $12,287.12/year (3.75%) and 250 Shuter $42,773.05/year (3.51%). Rent estimates and seller claims are not independently verified collected income; unknown expenses are not zero. Original article and sources follow.
Eight real properties—and the cash-flow conditions that matter
By Yossi Kaplan, MBA | RIGHT AT HOME REALTY. Research snapshot: November 14, 2026. A property that pays for itself should do more than produce an attractive rent-to-price ratio. Rent needs to cover the bills you actually pay, with room for vacancy, repairs and replacement equipment. This review separates covering the mortgage from producing resilient rental cash flow.
The sample includes eight active residential sale listings: three condos, three houses and two residential income properties. All are within the preferred Toronto area between the Humber and Don rivers, Lake Ontario and Highway 401. No outside-area properties were added to fill the list. This is a selected research sample, not every available Toronto investment. Prices are asking prices, not transaction values; no completed-sale or completed-lease prices are used. Availability and terms can change. [1]
No proven 20%-down cash-flow winner
At the assumptions below, one of eight properties passes the narrow carry test with 20% down, but none stays positive after prudent reserves. At 50% down, all eight pass the narrow test; two stay positive after reserves. All eight are positive in the all-cash operating model. These are conditional calculations—not eight verified self-funding investments. None has independently verified collected rent and a complete expense package.
Two definitions of “pays for itself”
- Narrow carry = monthly mortgage principal and interest + annual municipal property tax ÷ 12 + condo maintenance fee + owner-bill allowance. Narrow surplus = model rent minus this carry.
- Prudent surplus = narrow surplus minus landlord insurance, vacancy, repairs/capital replacement reserves and management allowance. It remains an estimate before income tax, appreciation and transaction costs.
- Tenant-paid utilities are excluded where the rental evidence expressly assigns them to the tenant. Unknown responsibility is not treated as zero: the model includes an unresolved owner-bill contingency. That is a conservative assumption, not a claim about actual lease obligations.
- A positive result is conditional on the inputs. It does not establish rent collection, lawful units, vacant possession, market-rent reset rights, lender approval or that missing expenses fit inside the allowance.
Financing: 5.50%, 25 years, Canadian compounding
Every financed scenario uses an illustrative 5.50% nominal annual rate, compounded semi-annually, monthly payments and 25-year amortization. A rental-focused mortgage broker's November 2026 published A-lender range for one-to-four-unit rentals is 4.50%–5.50%; this review uses the upper end, not a personalized rate quote. Borrower qualification, property condition, lawful unit configuration and 80% loan-to-value availability require lender approval. No interest-only loan, vendor mortgage, refinancing or appreciation is used to create a positive result. [2]
Calculations were executed using i = (1 + 0.055/2)^(2/12) ? 1 and payment = loan × i ÷ (1 ? (1+i)^?300). The payment is $610.39 monthly per $100,000 borrowed. The 20%-down case borrows 80% of asking price; 50/50 borrows 50%; all cash has no mortgage. Unrounded inputs drive every row; displayed components may differ by a cent due to rounding.
Expense assumptions—not verified operating statements
- Condos: $50 monthly landlord/unit insurance; vacancy 5%, interior repairs/capital reserve 5%, management 8% of model rent. Prudent extra deduction = $50 + 18% of rent. Condo building insurance in maintenance is not duplicated by the separate landlord/unit allowance.
- Houses: $150 monthly insurance; vacancy 5%, repairs/capital reserve 10%, management 8%. Prudent extra deduction = $150 + 23% of rent.
- Residential income properties: $250 monthly insurance; vacancy 5%, repairs/capital reserve 10%, management 8%. Prudent extra deduction = $250 + 23% of rent.
- Insurance is a budgeting assumption, not a quote. Management is an assumed all-in planning allowance, not a vendor proposal; actual fees, service taxes and leasing charges may exceed it. Self-management is work, not automatically free.
- Owner-bill contingencies are identified for every property. Heat/water already included in condo fees are not counted twice. Actual leases and bills must replace each placeholder. Unknown special assessments, immediate renovations and major deferred repairs are not assumed covered by ordinary monthly reserves.
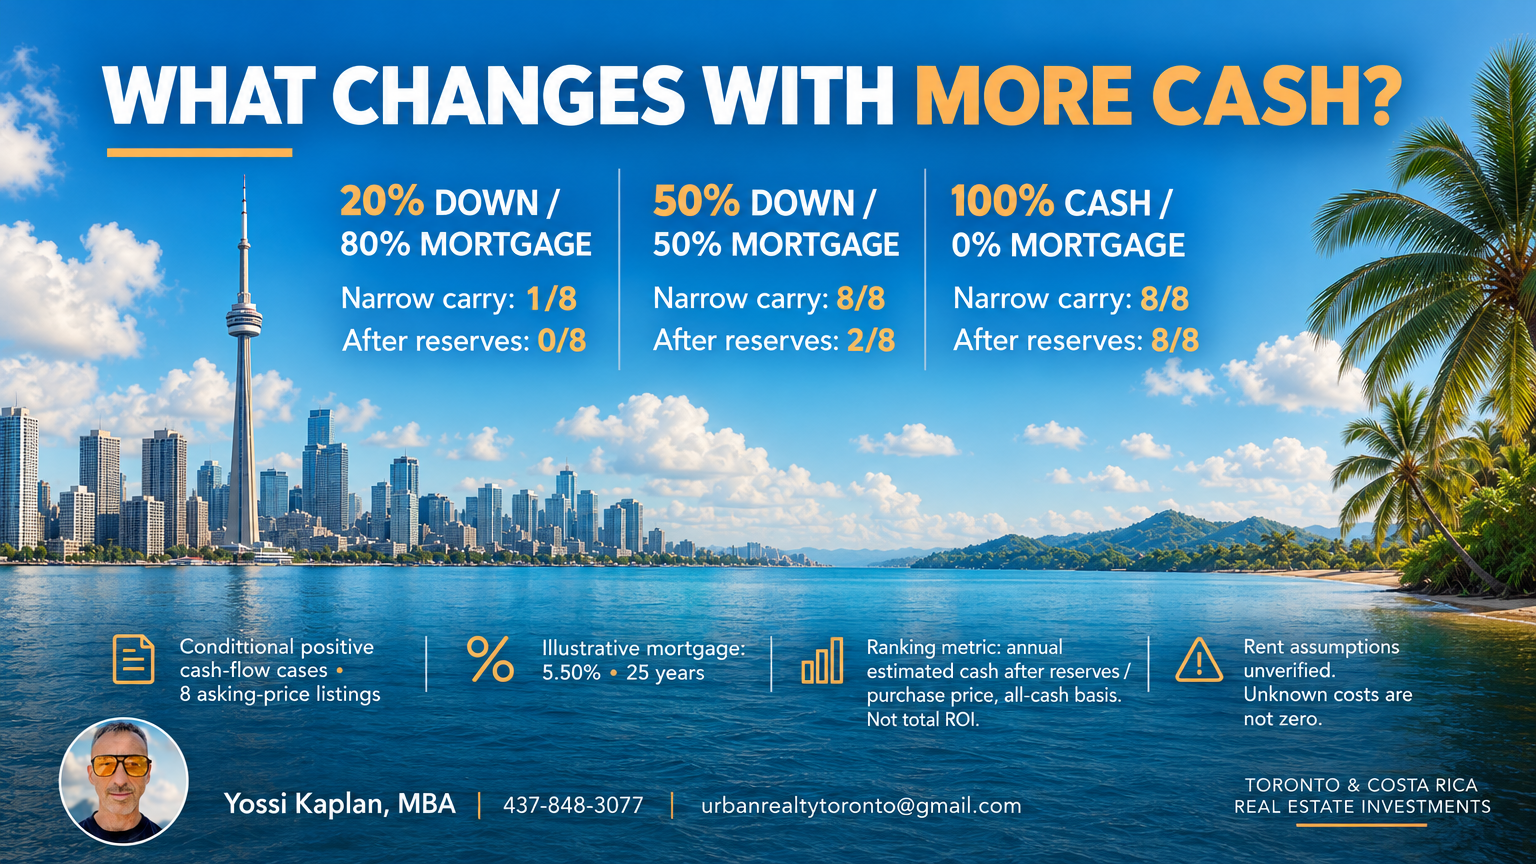
Conditional model positives for the same eight asking-price properties—not confirmed self-funding investments. AI-generated explanatory graphic.
1. Condo: 419–38 Joe Shuster Way
Actual MLS listing photograph for suite 419; building exterior, not the suite interior.
View 419–38 Joe Shuster Way — MLS W14123028
Active sale MLS W14123028 | Asking $328,000 | South Parkdale | One bedroom, MLS size band 0–499 sq. ft. Estimated model rent: $2,050 monthly. Evidence: active same-building one-bedroom 1220–38 Joe Shuster Way, MLS W14118086, also 0–499 sq. ft., asking $2,050. This is asking-rent evidence, not collected subject income; layout, floor, condition and lease terms need matching. Current subject tenancy and actual rent are unverified. [1]
Tax: $1,557.64 annually (2026), or $129.80 monthly. Maintenance: $377.27 monthly; heat and water are marked included. Hydro responsibility is unknown, so $100 monthly is budgeted for unresolved owner bills without duplicating heat/water. Prudent additions: $50 insurance + $369 percentage reserves monthly.
Monthly CAD. Cash equity excludes closing costs and working capital. Positive figures are conditional.
| Scenario / purchase equity | Mortgage | Narrow carry | Narrow surplus | Prudent surplus |
|---|---|---|---|---|
| 20% / $65,600 | $1,601.67 | $2,208.74 | ?$158.74 | ?$577.74 |
| 50% / $164,000 | $1,001.04 | $1,608.12 | +$441.88 | +$22.88 |
| Cash / $328,000 | $0.00 | $607.07 | +$1,442.93 | +$1,023.93 |
Conditional qualifiers: narrow test at 50% and cash; prudent test at 50% and cash. The financed prudent cushion is only $22.88. At an illustrative 6.50% rate with the same amortization it becomes ?$74.58 monthly. Review the status certificate, reserve fund, assessments and actual lease; this is not a resilient financed result.
2. Condo: 1616–215 Queen Street West
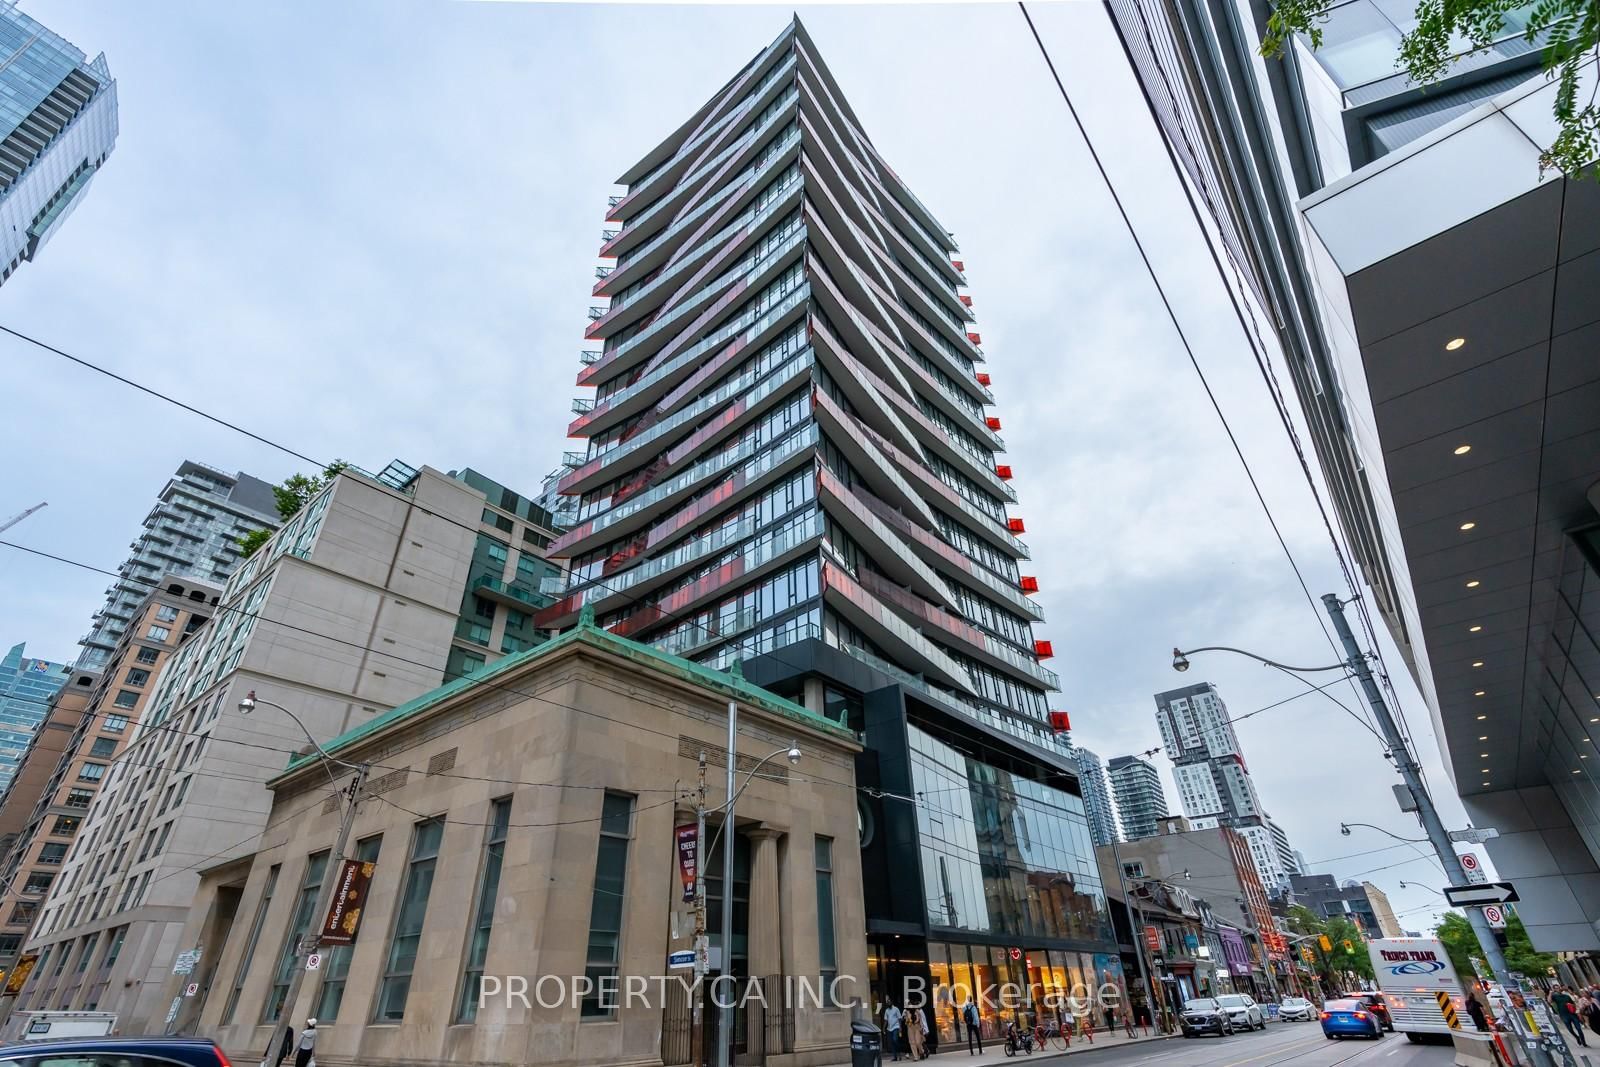
Actual MLS listing photograph for suite 1616; building exterior, not the suite interior.
View 1616–215 Queen Street West — MLS C13836430
Active sale MLS C13836430 | Asking $329,000 | Waterfront Communities C1 | Studio, 0–499 sq. ft. Estimated model rent: $1,900 monthly, supported by active same-building studio 707–215 Queen Street West, MLS C14178552, asking $1,900. A furnished studio asking $1,995 was not adopted; furnishing and layout can distort comparisons. Collected subject rent is not verified. [1]
Tax: $1,825 annually (2025), or $152.08 monthly; obtain the current bill. Maintenance: $299 monthly. Heat, hydro and water inclusions are not confirmed in the returned fee fields. The model includes $200 monthly for unresolved owner bills, not a finding that those services are owner-paid. Prudent additions: $50 insurance + $342 percentage reserves monthly.
Monthly CAD; conditional model, not an actual operating statement.
| Scenario / purchase equity | Mortgage | Narrow carry | Narrow surplus | Prudent surplus |
|---|---|---|---|---|
| 20% / $65,800 | $1,606.55 | $2,257.63 | ?$357.63 | ?$749.63 |
| 50% / $164,500 | $1,004.09 | $1,655.18 | +$244.82 | ?$147.18 |
| Cash / $329,000 | $0.00 | $651.08 | +$1,248.92 | +$856.92 |
Conditional qualifiers: narrow test at 50% and cash; prudent test only with cash. Verify occupancy, floor plan, utility obligations and condominium finances. Covering the mortgage and fees does not leave a prudent financed surplus here.
3. Condo: 712–215 Queen Street West
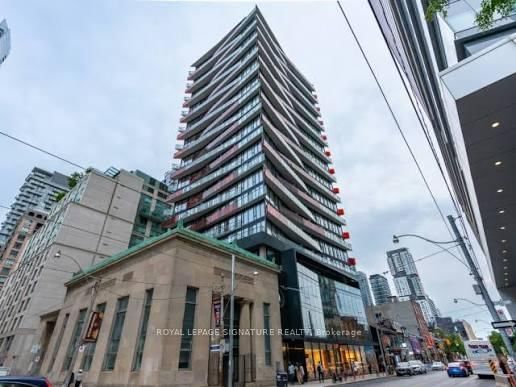
Actual MLS listing photograph for suite 712; building exterior, not the suite interior.
View 712–215 Queen Street West — MLS C13873450
Active sale MLS C13873450 | Asking $339,000 | Waterfront Communities C1 | Small suite/studio, 0–499 sq. ft.; bedroom count is unspecified in the sale feed. Estimated model rent: $1,900 monthly using active studio 707–215 Queen Street West, MLS C14178552. Confirm the subject floor plan before relying on this comparator. These two Queen Street purchases are separate candidates but concentrate exposure in the same building. No subject rent collection is verified. [1]
Tax: $1,790 annually (2025), or $149.17 monthly. Maintenance: $313 monthly. Utility inclusions and tenant responsibility are unresolved; owner-bill contingency $200 monthly. Prudent additions: $50 insurance + $342 percentage reserves monthly.
Monthly CAD; equity excludes closing costs.
| Scenario / purchase equity | Mortgage | Narrow carry | Narrow surplus | Prudent surplus |
|---|---|---|---|---|
| 20% / $67,800 | $1,655.38 | $2,317.55 | ?$417.55 | ?$809.55 |
| 50% / $169,500 | $1,034.61 | $1,696.78 | +$203.22 | ?$188.78 |
| Cash / $339,000 | $0.00 | $662.17 | +$1,237.83 | +$845.83 |
Conditional qualifiers: narrow test at 50% and cash; prudent test only with cash. Under identical rent assumptions, its higher asking price and fee leave less room than suite 1616. This financial comparison does not replace checking the physical unit, status certificate and lease.
4. House: 82 Beechwood Avenue
Photo verification note: The supplied exterior image has been omitted because its visible house number conflicts with the listing address. Confirm the address and property details with the listing representative.
View 82 Beechwood Avenue — MLS W14105658
Active sale MLS W14105658 | Asking $609,000 | Rockcliffe-Smythe | Detached, two bedrooms plus an additional bedroom field, MLS size band 700–1,100 sq. ft. Estimated model rent: $2,800 monthly as a single whole-house letting. Evidence: active two-bedroom entire-house rental 71 Bernice Crescent, MLS W13828678, in Rockcliffe-Smythe, asking $2,800. It is a neighbourhood comparator, not the same property. Condition and size differences can materially change achievable rent. Current occupancy and contractual rent are unverified. No separate basement income is assumed. [1]
Tax: $3,076.91 annually (2026), or $256.41 monthly. No condo fee modelled for this freehold house. Unknown utilities and recurring owner bills receive a $350 monthly contingency rather than zero. Prudent additions: $150 insurance + $644 percentage reserves monthly.
Monthly CAD; whole-house letting applies only if lawful possession permits it.
| Scenario / purchase equity | Mortgage | Narrow carry | Narrow surplus | Prudent surplus |
|---|---|---|---|---|
| 20% / $121,800 | $2,973.83 | $3,580.24 | ?$780.24 | ?$1,574.24 |
| 50% / $304,500 | $1,858.64 | $2,465.05 | +$334.95 | ?$459.05 |
| Cash / $609,000 | $0.00 | $606.41 | +$2,193.59 | +$1,399.59 |
Conditional qualifiers: narrow test at 50% and cash; prudent test only with cash. A lower detached entry price does not automatically produce self-funding leveraged ownership. Obtain inspection, insurance and site-specific flood-risk information, together with actual leases and bills.
5. House: 56 Beechwood Avenue
Actual MLS listing photograph — 56 Beechwood Avenue.
View 56 Beechwood Avenue — MLS W13777726
Active sale MLS W13777726 | Asking $649,000 | Rockcliffe-Smythe | Detached bungalow with an advertised basement in-law suite. Model income: $2,700 monthly, the listing's stated existing income from two tenants—not a market-rent reset. This is seller/listing-reported income, not independently verified in-place rent. Leases, ledger, arrears, deposits and collection records were not supplied. The in-law suite's legal status is unverified. The property is advertised as-is, where-is. [1]
Tax: $2,740 annually (2025), or $228.33 monthly. No condo fee. Unknown utility responsibility and owner bills receive a $350 monthly contingency. Prudent additions: $150 insurance + $621 percentage reserves monthly. Normal reserves are not a substitute for funding immediate as-is repairs. Advertised vendor financing is not used in these scenarios.
Monthly CAD using advertised existing income, subject to rent-roll verification.
| Scenario / purchase equity | Mortgage | Narrow carry | Narrow surplus | Prudent surplus |
|---|---|---|---|---|
| 20% / $129,800 | $3,169.15 | $3,747.49 | ?$1,047.49 | ?$1,818.49 |
| 50% / $324,500 | $1,980.72 | $2,559.05 | +$140.95 | ?$630.05 |
| Cash / $649,000 | $0.00 | $578.33 | +$2,121.67 | +$1,350.67 |
Conditional qualifiers: narrow test at 50% and cash; prudent test only with cash. Do not replace the existing $2,700 with new-tenant asking rents merely because ownership changes. The actual leases and lawful rent position govern the starting analysis.
6. House: 21 Porter Avenue
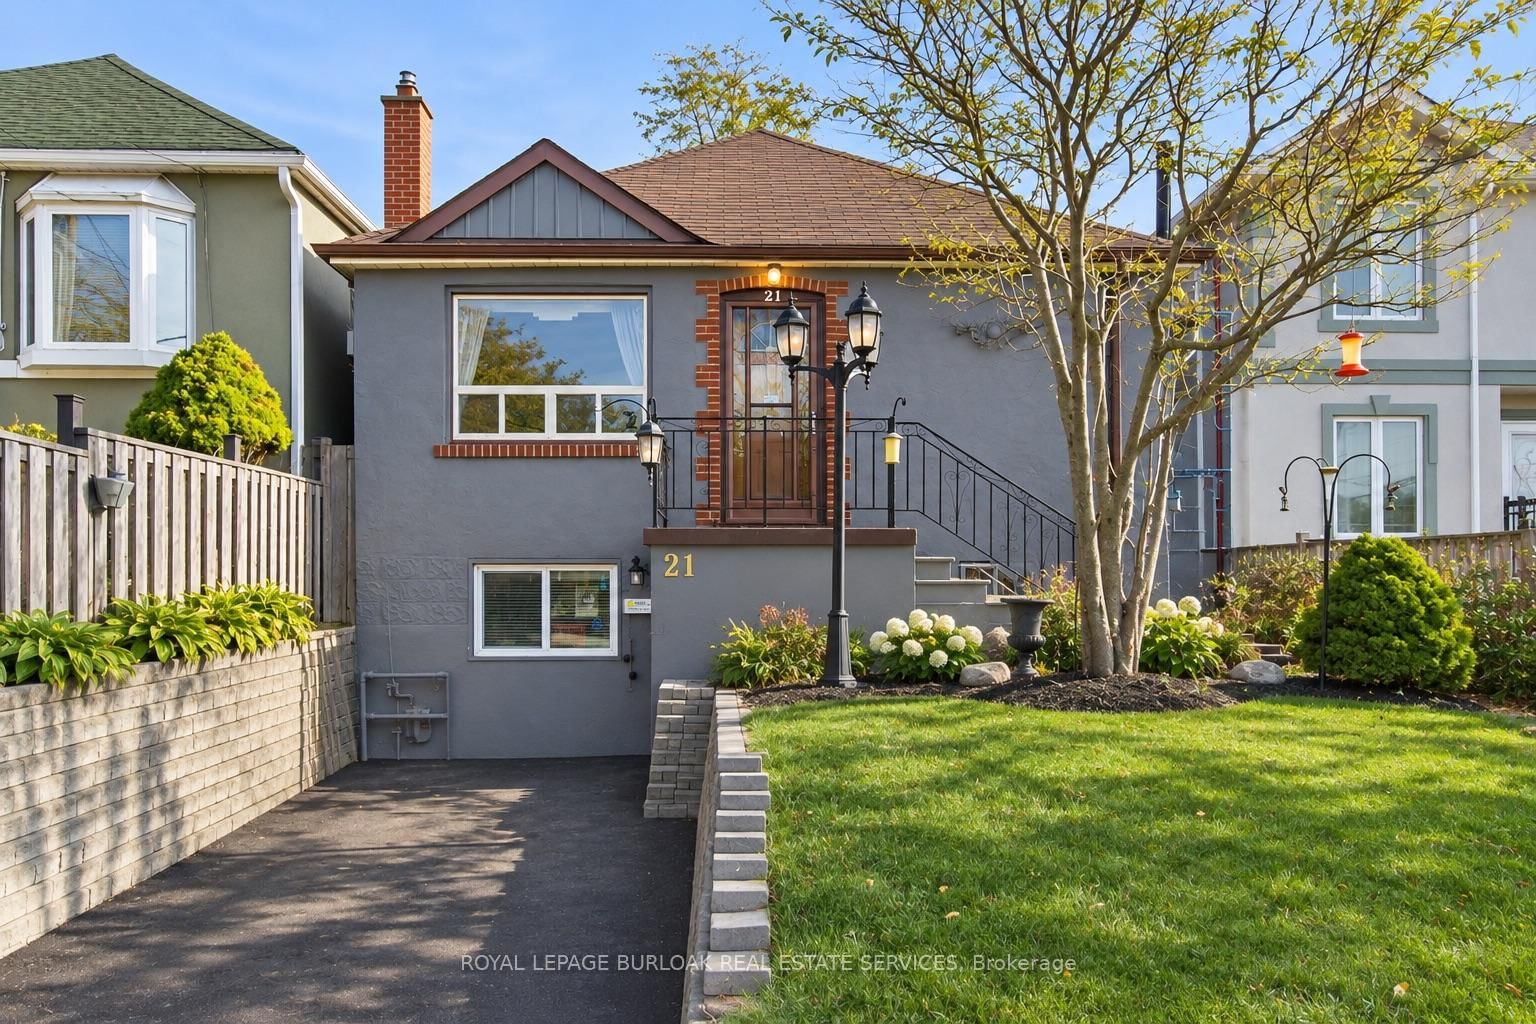
Actual MLS listing photograph — 21 Porter Avenue.
View 21 Porter Avenue — MLS W14179198
Active sale MLS W14179198 | Asking $649,900 | Rockcliffe-Smythe | Detached two-plus-one-bedroom house with an advertised separate basement apartment and renovation opportunity. Estimated model rent: $2,800 monthly for one whole-house letting, using active 71 Bernice Crescent, MLS W13828678. No second rent is added. This does not assume the basement is lawful, that occupants can be displaced or that separate tenancies can be consolidated. Current tenancy, configuration and condition must permit the modelled strategy; otherwise these outputs do not apply. [1]
Tax: $3,161.33 annually (2026), or $263.44 monthly. No condo fee. Tenant utility obligations are unknown; $350 monthly is budgeted for unresolved owner bills. Prudent additions: $150 insurance + $644 percentage reserves monthly. Initial renovation cash is additional, not hidden inside the ordinary reserve.
Monthly CAD; single-house rental is a conditional strategy, not confirmed possession.
| Scenario / purchase equity | Mortgage | Narrow carry | Narrow surplus | Prudent surplus |
|---|---|---|---|---|
| 20% / $129,980 | $3,173.55 | $3,786.99 | ?$986.99 | ?$1,780.99 |
| 50% / $324,950 | $1,983.47 | $2,596.91 | +$203.09 | ?$590.91 |
| Cash / $649,900 | $0.00 | $613.44 | +$2,186.56 | +$1,392.56 |
Conditional qualifiers: narrow test at 50% and cash; prudent test only with cash. Obtain the actual rent roll, inspection and possession documentation rather than underwriting an imagined vacant property.
7. Residential income property: 250 Shuter Street
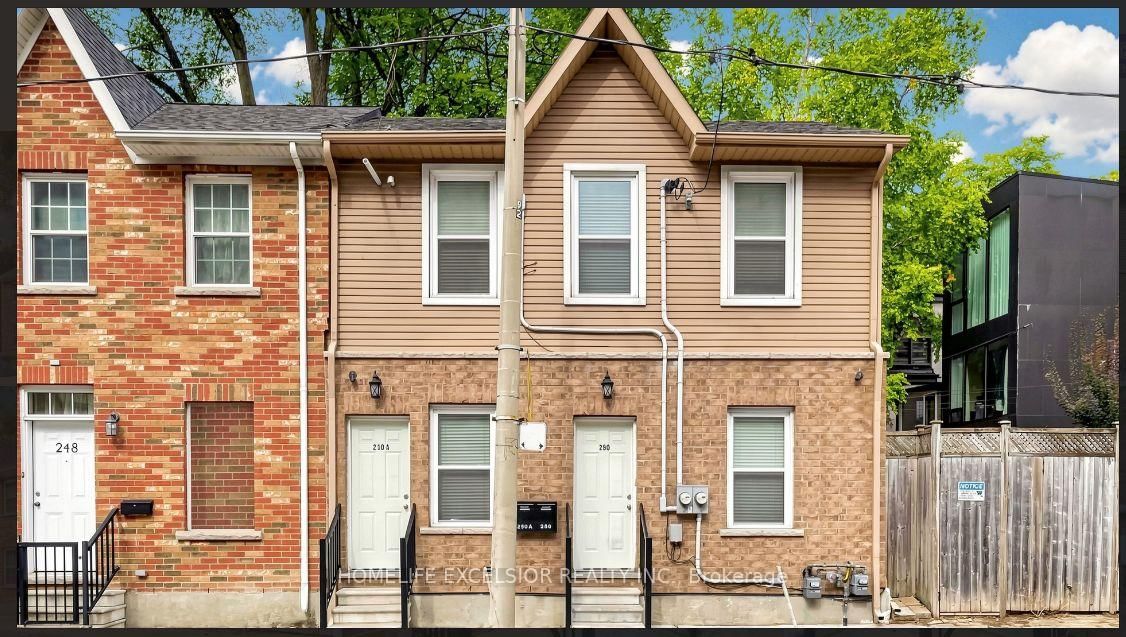
Actual MLS listing photograph — 250 Shuter Street; adjacent entrances are visible.
View 250 Shuter Street — MLS C13852988
Active sale MLS C13852988 | Asking $1,220,000 | Moss Park | Listed as a legal two-unit duplex; municipal and lender verification is still required. The sale description identifies a four-bedroom main/basement suite and a two-bedroom second-floor suite. Estimated gross model rent: $5,700 monthly from the property's own active rental asks: MLS C14176586, main/basement at 250 Shuter, $3,500; MLS C14176942, second-floor two-bedroom at 250A Shuter, $2,200. Matching descriptions link the suites, but reconcile 250/250A against title, plans and leases. Asking rents do not prove vacancy or collection. [1]
Tax: $5,094.95 annually (2026), or $424.58 monthly. No condo fee. Both rental advertisements exclude utilities and describe individual metering; tenant-paid metered consumption is excluded. A $150 monthly contingency remains for water, common or unrecovered owner charges not established by signed leases and bills. The sale listing says hot-water tanks are owned, so no invented tank rental is added. Prudent additions: $250 insurance + $1,311 percentage reserves monthly.
Monthly CAD using active asking rents—not signed or collected rents.
| Scenario / purchase equity | Mortgage | Narrow carry | Narrow surplus | Prudent surplus |
|---|---|---|---|---|
| 20% / $244,000 | $5,957.42 | $6,532.00 | ?$832.00 | ?$2,393.00 |
| 50% / $610,000 | $3,723.39 | $4,297.97 | +$1,402.03 | ?$158.97 |
| Cash / $1,220,000 | $0.00 | $574.58 | +$5,125.42 | +$3,564.42 |
Conditional qualifiers: narrow test at 50% and cash; prudent test only with cash. Property-specific rental asks are useful evidence but do not turn this financed prudent deficit into a surplus. At 6.50%, the 50%-down prudent result is ?$521.50 monthly.
8. Residential income property: 301 Dupont Street
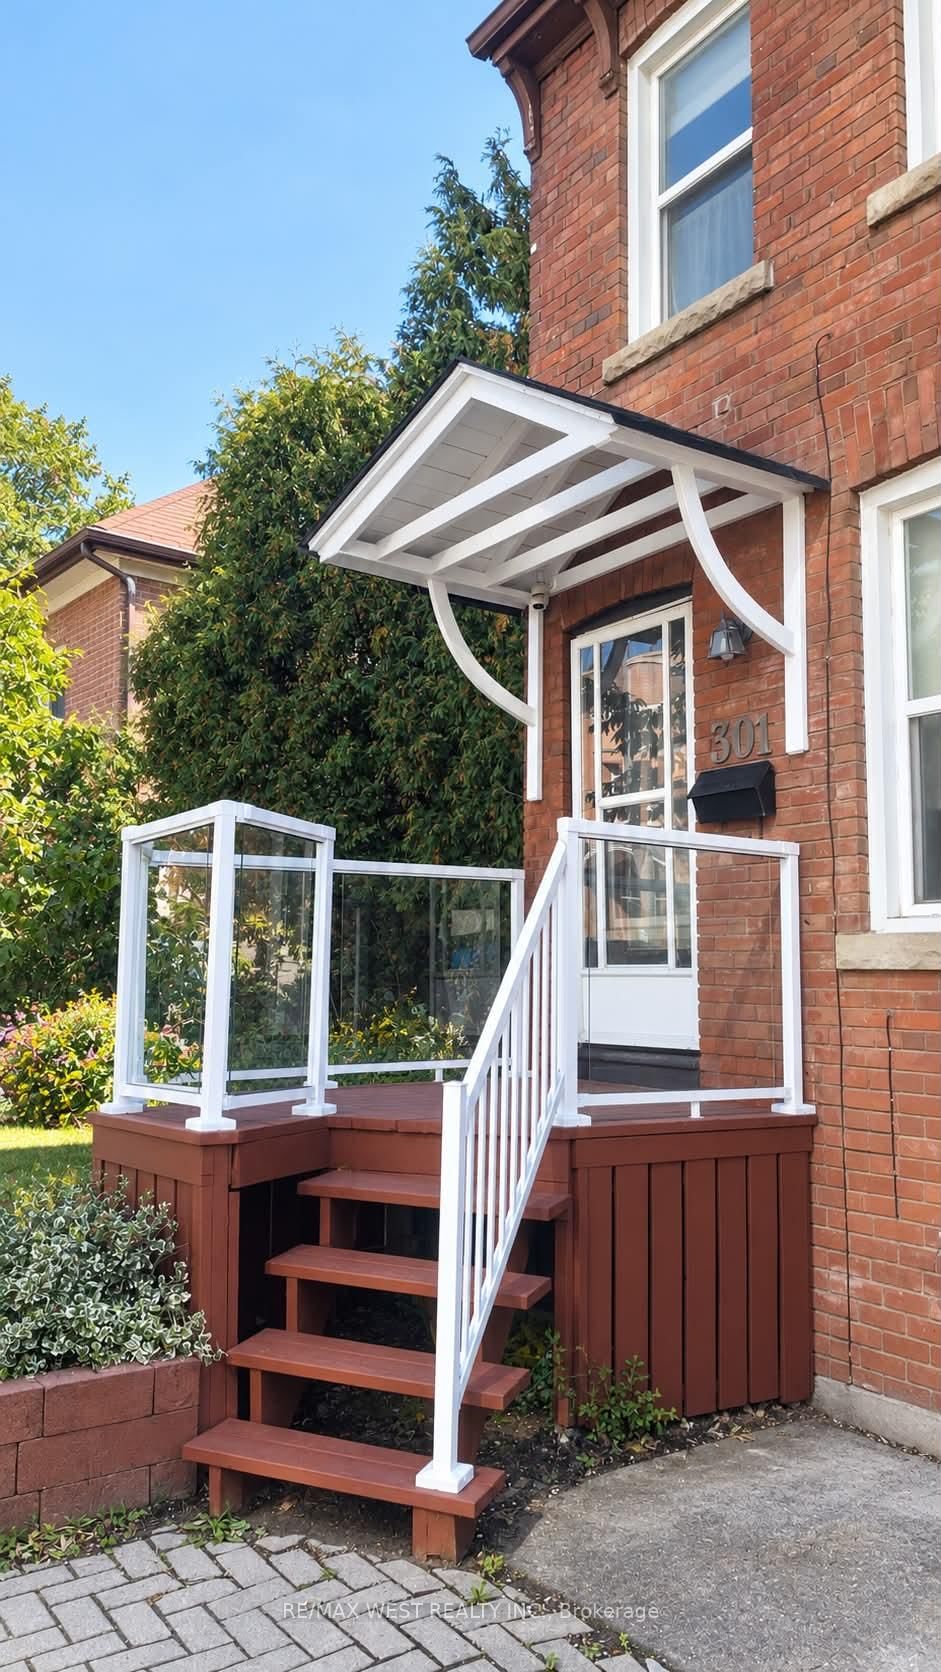
Actual MLS listing photograph — the 301 Dupont entrance; selected to show the correct house number rather than the neighbouring entrance.
View 301 Dupont Street — MLS C13950348
Active sale MLS C13950348 | Asking $1,299,000 | Annex | MLS type Duplex, while remarks describe three self-contained apartments: two two-bedroom units and an upper three-bedroom unit. This mismatch matters: it is an income-property candidate, not a verified legal triplex. The listing advertises annual rental income of $97,080, or $8,090 monthly. It describes established rentals, but signed leases, unit-by-unit ledger and collection evidence were not supplied. This is seller/listing-reported income used conditionally, not independently verified in-place rent. [1]
Tax: $6,108 annually (2026), or $509 monthly. No condo fee. Utilities and the full expense statement are unknown; a $600 monthly unresolved owner-bill contingency is used, not a verified operating cost. Prudent additions: $250 insurance + $1,860.70 percentage reserves monthly. The listing's cap-rate claim is not adopted because the supporting expense evidence is missing.
Monthly CAD; advertised annual income ÷ 12. Verify leases and lawful unit configuration.
| Scenario / purchase equity | Mortgage | Narrow carry | Narrow surplus | Prudent surplus |
|---|---|---|---|---|
| 20% / $259,800 | $6,343.19 | $7,452.19 | +$637.81 | ?$1,472.89 |
| 50% / $649,500 | $3,964.49 | $5,073.49 | +$3,016.51 | +$905.81 |
| Cash / $1,299,000 | $0.00 | $1,109.00 | +$6,981.00 | +$4,870.30 |
Conditional qualifiers: narrow test at every equity level; prudent test at 50% and cash. This is the only 20%-down narrow positive in the sample, and it still fails the prudent test at that leverage. At 6.50%, the 50%-down prudent surplus is $519.79 monthly. Request the rent roll, leases, bills, insurance quote and municipal configuration records first.
What survives the tests?
Conditional model positives—not independently verified self-funding investments.
| Metric | 20% down | 50% down | All cash |
|---|---|---|---|
| Narrow surplus positive | 1 of 8 | 8 of 8 | 8 of 8 |
| Prudent surplus positive | 0 of 8 | 2 of 8 | 8 of 8 |
| Independently verified self-funding properties | 0 confirmed | 0 confirmed | 0 confirmed |
At 50% down, the prudent positives are 301 Dupont and 419–38 Joe Shuster. They are not equivalent: Dupont has the larger conditional cushion but unresolved unit status and seller-reported income; Joe Shuster's $22.88 cushion disappears with a small expense change. The other six show why rent can cover mortgage, taxes and basic bills while ownership still requires regular contributions after realistic reserves.
All cash is not a free property
Removing a mortgage removes a payment, not the cost of capital. Each cash case ties up the full asking price shown in its table, plus land-transfer taxes, legal fees, inspections, adjustments, initial repairs and working capital. The equity figures are not total cash-to-close. No borrowed down payment is assumed; if equity comes from a credit line, add its payments. Closing-cost and tax calculations need transaction-specific professional advice.
Annual prudent model surplus ÷ asking price; before closing costs, income tax and appreciation. Not a verified cap rate, guaranteed yield or total return.
| Property | Illustrative unlevered cash yield |
|---|---|
| 419–38 Joe Shuster Way | 3.75% |
| 1616–215 Queen St W | 3.13% |
| 712–215 Queen St W | 2.99% |
| 82 Beechwood Ave | 2.76% |
| 56 Beechwood Ave | 2.50% |
| 21 Porter Ave | 2.57% |
| 250 Shuter St | 3.51% |
| 301 Dupont St | 4.50% |
Compare these conditional yields with the after-tax return on other uses of the same capital, liquidity needs and concentration risk. Opportunity cost is the return forgone by tying up the purchase cash; it is not deducted here as a fabricated monthly bill. Appreciation is uncertain and does not pay this month's expenses. Principal repayment can build equity but is not spendable monthly surplus.
Stress the expenses as well as the mortgage
- The 6.50% examples are a separate one-percentage-point rate sensitivity, not a forecast or lender qualification test. All-cash results do not change with that rate but still change with rent, vacancy and operating costs.
- Every additional $100 of actual monthly owner cost reduces both surplus columns by $100. A contingency does not cap your exposure.
- Vacancy, repairs and management percentages are planning allowances. Extended non-payment, major repairs and condo assessments can exceed several years of ordinary reserves.
- A sale does not itself create a new tenancy or an automatic market-rent reset. Do not replace contractual rent with asking-rent comparators. Have tenancy documentation and possession strategy reviewed by an Ontario lawyer or qualified paralegal. [3]
Before making an offer, replace assumptions with documents
- Obtain signed leases, amendments, rent roll, ledger and collection evidence; verify deposits, arrears, included services and lawful rent-increase history.
- Confirm the actual occupancy and lawful possession available on closing. Separate entrances, listing photos and proposed uses do not establish vacant possession.
- Verify municipal use and building records, permitted configuration, fire/safety compliance and lender acceptance. Three kitchens or an in-law suite does not prove three lawful rental units.
- Get the current municipal tax bill, 12–24 months of utility and owner bills, insurance quotes, equipment contracts and service charges. Replace every placeholder used here.
- For condos, review the status certificate, budget, reserve-fund study, assessments, rental rules and exact fee inclusions. Do not charge heat or water twice in your model.
- Price inspection findings, initial capital work, closing costs and enough liquid reserves for a bad year. Confirm financing, legal and tax specifics with the appropriate professionals.
Buy the evidence, not the headline
The useful question is how much equity an investment needs, which bills the owner truly bears and what remains when optimistic assumptions are removed. This sample does not support a claim that conventional 20%-down investing reliably pays its own way. It identifies specific properties worth document review—and specific reasons not to confuse a positive carrying-cost calculation with dependable income.
Build a shortlist around your cash-flow target
Discuss your equity, objectives and due diligence with Yossi Kaplan, MBA, RIGHT AT HOME REALTY. [email protected] | +1 (437) 848-3077.
Research note: Live MLS active sale and asking-rental records were checked November 14, 2026. Source 1 is the current search entry point, not a permanent archive; exact MLS identifiers above are the audit trail. All 24 financing scenarios were calculated with Canadian semi-annual compounding. No inspections, independent rent-collection verification or complete expense audits were performed. This is educational investment analysis, not an appraisal, financing commitment, tax advice or promise of performance.
Sources
- Live MLS sale and active rental records checked November 14, 2026; exact MLS identifiers appear below. Current listing search—not a historical archive.
- LendCity investment-property mortgage rates; accessed November 14, 2026. November 2026 A-lender 1–4 unit rental range: 4.50%–5.50%. Not an individual quote.
- CLEO Steps to Justice: Learn if the new owner can raise your rent; accessed November 14, 2026.